A steady lead
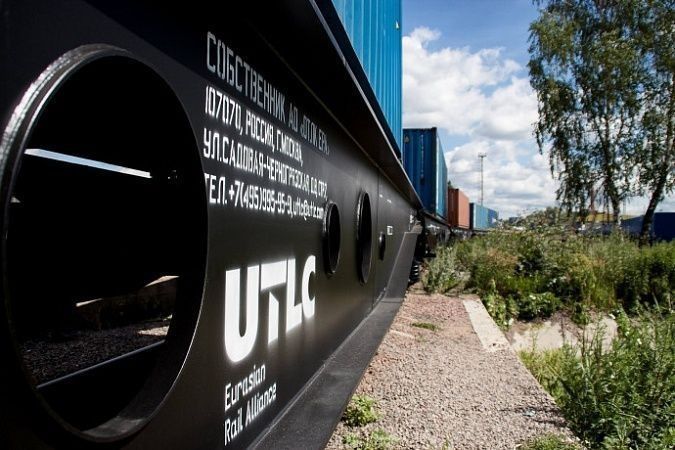
“The structure of container flows on the China–EU–China route, broken down by the main border crossings, shows the continuing lead of the Eurasian rail route using the Dostyk and Altynkol crossings,” UTLC ERA said in its 2025 annual report, published a day earlier. According to the company, 311,200 TEU, or 88.1% of the total, were carried along this route during the reporting period.
The Trans-Caspian International Transport Route (TITR) accounted for 41,500 TEU, or 11.7%. UTLC ERA notes growth on this corridor (up 14.4% year on year), driven by investment in infrastructure and a partial reorientation of cargo flows.
At the same time the route remains technologically difficult: relatively low throughput (around 120,000 TEU a year) and multiple transshipments limit its efficiency and make it dependent on the national operators synchronizing their actions, the company’s report says.
Rail container traffic between the EU and China along other routes has, on UTLC ERA’s figures, all but disappeared. At the Zabaikalsk and Naushki crossings there is “a substantial decline, linked to the reorientation of cargo flows onto other routes and to a general fall in overland transit volumes.” Shipments through the ports and stations of the Far East have ceased entirely in recent years. This too is linked to the reorientation of rail and port infrastructure toward import and export operations.
A market running on inertia
Total rail container traffic on the China–EU–China route along all rail routes fell 17.7% year on year in 2025, to 353,600 TEU. UTLC ERA attributes the downward trend to tighter economic measures against unfriendly countries, the development of alternative corridors, the emergence of new supply chains using various modes, and growing competition from shipping.
“At present the transit rail sector on the China–EU–China route is going through a downturn. The volumes that will fall to rail in future are being shaped by inertial growth in trade, by the evolution of the regulatory environment and by the gradual restoration of trade ties. Projected competitive dynamics in the sector will be determined by how volumes are distributed between the two key transport corridors — UTLC ERA’s core route and the TITR,” the company says.
Eurasia on the rise
At the same time, trade and economic engagement between the countries of the Eurasian Economic Union (EAEU) and China has been growing rapidly in recent years. The key factor has been the structural reorientation of the Customs Union states’ foreign trade toward the east amid mounting sanctions pressure from Western countries since 2022.
In 2025, 3.6 million TEU were carried on the China–EAEU–China route, with UTLC ERA accounting for 7.1%. “The rail container market on China–EAEU–China routes as a whole is entering a phase of early maturity. The pace of trade growth is gradually slowing. Positive dynamics are expected to be maintained over the long term, but market growth rates will slow (annual growth of around 0.5%). Under these conditions competition will intensify both within the rail mode — on price, speed and service quality — and between modes of transport,” the company forecasts.
- April 2026
- October 2026
- September 2026
- August 2026
- July 2026
- June 2026
- May 2026
- February 2026
- January 2026
- December 2025
- November 2025
- October 2025
- September 2025
- August 2025
- July 2025
- June 2025
- aprel-2025
- March 2025
- February 2025
- January 2025
- December 2024
- November 2024
- September 2024
- August 2024
- July 2024
- June 2024
- May 2024
- April 2024
- March 2024
- February 2024
- January 2024
- December 2023
- November 2023
- October 2023
- September 2023
- August 2023
- July 2023
- June 2023
- May 2023
- April 2023
- March 2023
- February 2023
- January 2023
- December 2022
- November 2022
- October 2022
- September 2022
- August 2022
- July 2022
- June 2022
- May 2022
- April 2022
- March 2022
- February 2022
- January 2022
- December 2021
 Read next content